October Heat Map: Prices Cooled in 43 of 77 Central Texas ZIP Codes. Here's What It Means for You
October Heat Map: Prices Cooled in 43 of 77 Central Texas ZIP Codes. Here's What It Means for You
Market Watch | Friday, November 13, 2026 | By Christi Davidson
Every month, my friends at Texas National Title publish the MLS Statistics Heat Map, which compares each Central Texas ZIP code's median sales price with the same month a year earlier. The October 2026 report is in, and the headline is clear: prices are softer than a year ago in more of our market than not.
Of the 77 ZIP codes Texas National Title tracks:
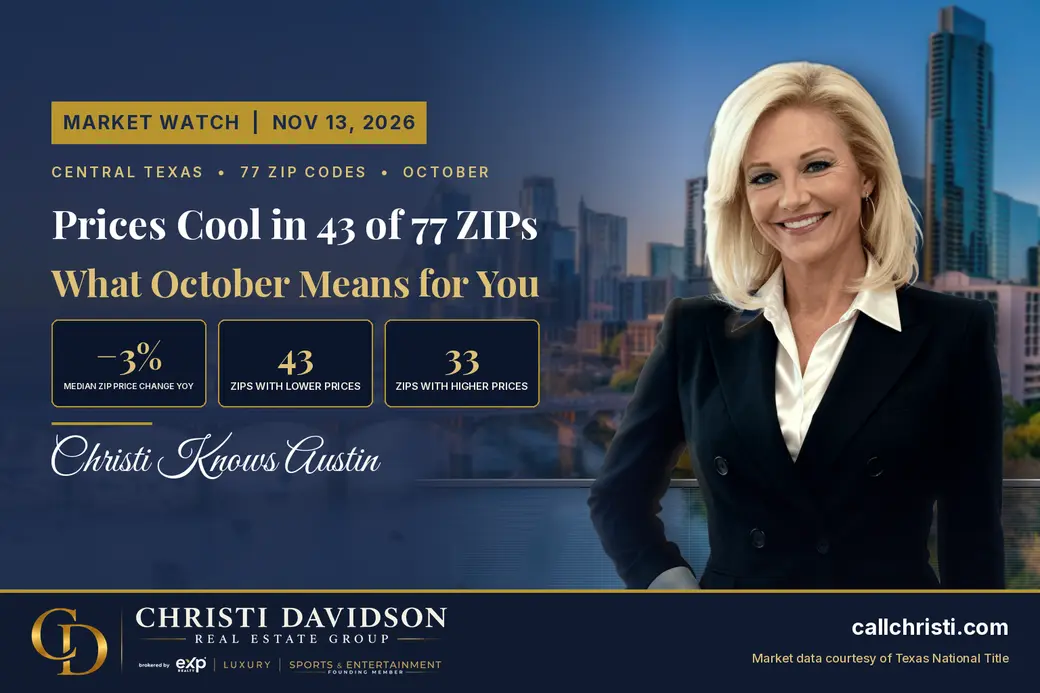
- 43 ZIPs had a lower median sales price than in October 2025
- 33 ZIPs were higher
- 1 ZIP (78645, Lago Vista) was exactly flat at 0%
- The typical ZIP was down 3% year over year
September looked almost the same: 30 ZIPs rose, 4 held flat, and 43 declined, with the typical ZIP down 2%. The regional story hasn't changed. This has been a year of flat to slightly lower prices, not a sharp correction. What did change is where the gains and declines showed up.
That's a balanced-to-buyer-leaning market overall, but the averages hide a lot. In over 28 years of helping families buy and sell in Central Texas, I've learned that real estate is never one market. It's dozens of neighborhoods moving at their own pace. Here's how October looked, area by area. For the complete ZIP-by-ZIP tables, see Texas National Title's October report (PDF) and September report (PDF).
What held up, and what stayed soft
The two-month view is what separates a real trend from a noisy month.
Held up in both September and October: East Austin 78721, Circle C 78739, Steiner Ranch 78732, Bastrop 78602, and Lockhart 78644. These are established areas where prices were already higher than a year ago in September, and they stayed higher in October.
Stayed soft in both months: Pflugerville 78660, Hutto 78634, Taylor 76574, Georgetown's 78633, North Austin 78727, and East Austin 78702, which was down 12% both months. Several established, close-in neighborhoods held their value. Many northern and eastern suburbs stayed soft for a second straight month, and that's where buyers currently have the most room to negotiate.
The biggest swings
Each ZIP's figure is a median for that month, so a handful of sales can move the number a lot. Treat these as a signal to look closer, not as a trend.
- 78705 (UT/West Campus) jumped from a September median of $307,500 to $950,000, up 175% from a year ago. This area is mostly condos, so a few house sales can change the median completely.
- 78753 (North Austin/Heatherwilde) went from up 25% in September to down 16% in October.
- 78741 (East Riverside/Montopolis) went from up 38% in September to down 42% in October.
Swings like these tell us what sold, not what a particular home is worth.
Area by area
These are the highlights by area. "Typical ZIP" means the median of the ZIP-level changes in that area, not a sales-weighted average. For every ZIP's median price and year-over-year change, use the October and September printable reports linked above.
Central Austin: up overall, with big swings
The typical central ZIP was up 13%, and 7 of 11 central ZIPs posted gains.
- Rising: Hyde Park 78751 (+41%), East Austin 78721 (+39%), Rosedale/Brentwood 78756 (+29%), Downtown 78701 (+28%), 78723 (+13%), Tarrytown/Clarksville 78703 (+6%)
- Softening: 78702 (−12%), South Austin 78704 (−13%), 78722 (−24%), 78741 (−42%)
78705's +175% is the small-sample swing noted above. I wouldn't read it as a trend.
West Austin & Lake Travis: steady at the top
The typical ZIP was up 4.5%. Westlake 78746 rose 7% to a $1,845,000 median, the highest in the report. Lakeway/Lake Travis 78734 was up 36%, Spicewood 78669 up 15%, and 78732 up 7%. 78738 was nearly flat (+2%), as was Lago Vista 78645 (0%). On the soft side were 78733 (−3%) and 78730 (−10%).
South & Southwest Austin: mostly holding
The typical ZIP was up 3%. Circle C 78739 (+17%), 78735 (+11%), 78748 (+10%), 78745 (+6%), and 78749 (+3%) all gained. Prices eased in 78747 (−3%), 78736 (−10%), Manchaca 78652 (−13%), and 78737 (−20%).
North & Northwest Austin: the softest part of the core
The typical ZIP was down 10%, and 11 of 13 ZIPs were lower. Exceptions were 78759 (+28%) and 78752 (+5%). Declines ran from 78726 (−2%) to 78750 (−20%), with 78731 (−16%), 78753 (−16%), and 78727 (−18%) in between. If North Austin has been on your wish list, this is a good time to take a fresh look.
East Austin & Eastern Travis: value with leverage
The typical ZIP was down 7%. 78725 rose 24% and 78744 rose 4%. Manor 78653 (−4%), Pflugerville 78660 (−10%), Del Valle 78617 (−11%), and 78724 (−16%) were lower.
Williamson County, including Taylor: buyers have room to negotiate
The typical Williamson ZIP was down 7.5%, and 10 of 12 ZIPs were lower. Only Round Rock 78664 (+11%) and Cedar Park 78613 (+3%) gained.
- Taylor (76574): median $295,900, down 9%, among the most affordable medians in the report
- Hutto 78634: $301,649 (−13%) | Liberty Hill 78642: $474,900 (−13%)
- Georgetown: 78628 (−11%), 78626 (−8%), 78633 (−4%)
- Round Rock 78681: −11% | Round Rock 78665: −6% | Leander 78641: −2% | Jarrell 76537: −7%
If you've been watching Taylor, Hutto, or Georgetown from the sidelines, this is a window worth a conversation.
Hays County: a split decision
The typical Hays ZIP was down 1%. Driftwood 78619 (+54%, a small, high-end sample), Buda 78610 (+9%), and Wimberley 78676 (+1%) rose. Kyle 78640 (−3%), San Marcos 78666 (−21%), and Dripping Springs 78620 (−21%) fell.
Surrounding areas
Outside the core, the typical ZIP was up 2%. New Braunfels 78130 (+34%), Lockhart 78644 (+29%), Smithville 78957 (+20%), and Bastrop 78602 (+6%) gained. Elgin 78621 (−11%), Marble Falls 78654 (−14%), and Burnet 78611 (−15%) softened.
What this means for buyers
- You have leverage in most of the market. With 43 of 77 ZIPs below last year, ask about price, closing costs, and rate buydowns. Your best room to negotiate is in the suburbs that stayed soft for two months, including Pflugerville, Hutto, Taylor, and parts of North Austin.
- Shop by ZIP, not by headline. The same budget buys very differently in 78759 than in 78727, just a few miles apart.
- The holidays are a buyer's window. Buyers who act in November and December usually face less competition than they will in March. Get pre-approved before the holidays, because lenders, appraisers, and title companies slow down in December.
What this means for sellers
- Price to your ZIP, not to 2022. If your area has held up for two months, like Circle C, Steiner Ranch, or East Austin's 78721, you can price with more confidence. In softening areas, the first two weeks on market matter most. Listings that start right sell, and those that don't end up chasing the market down.
- Presentation and flexibility win. Buyers have choices. Condition, staging, and a willingness to help with closing costs are what separate the homes that sell from the ones that sit.
- Rising ZIPs still need strategy. Even in up-trending areas, buyers are disciplined, and a sharp list price brings stronger offers.
Let's talk about your ZIP code
Every home and every block is different. If you'd like a personalized report on what's happening on your street — not just in your ZIP code — or what your home could sell for today, call or text me at 512-426-7399 or visit callchristi.com.
A big thank-you to Tracy Blair and the team at Texas National Title for this data. Explore the interactive heat map, download the October printable report (PDF) or the September report (PDF), or catch up on the 5-Year Trends.
Christi Davidson
Your Trusted Real Estate Advisor for Life
Christi Davidson Real Estate Group | brokered by eXp Realty | eXp Luxury | Sports & Entertainment Founding Member
callchristi.com | 512-426-7399 | TX License #467962
Categories
Recent Posts
GET MORE INFORMATION
